

Written by: Christopher Gannatti, CFA, Global Head of Research
Key Takeaways
- The WisdomTree Japan Hedged Equity Fund (DXJ) ranks #1 in the Morningstar Japan Stock category over the past 5 years, 10 years and since inception, underscoring the strength of its exporter-focused, dividend-weighted strategy.
- Japan's investment outlook is supported by record corporate profits, pro-growth policy and corporate reforms, while valuations remain attractive relative to global markets.
- DXJ's currency hedge lets investors access Japan's equity upside while minimizing the impact of yen fluctuations.
Japan's equity market has spent the past decade dismantling assumptions that took a generation to form. Deflationary expectations had become the default lens, and with them, the presumption that Japanese equities had little to offer.
Japan was, for most, a tactical consideration at best, an interesting country allocation but rarely a conviction position.
The contrast with that earlier era is now difficult to ignore. Policy is pulling in the same direction as corporate behavior, the 1989 peak has finally been surpassed,1 and Japan's recovery is being led by exactly the industries, technology, defense and global export champions, that give it structural rather than merely cyclical credibility.
In such a dynamic market, it has been amazing to look at the track record of the WisdomTree Japan Hedged Equity Fund (DXJ).
The Results
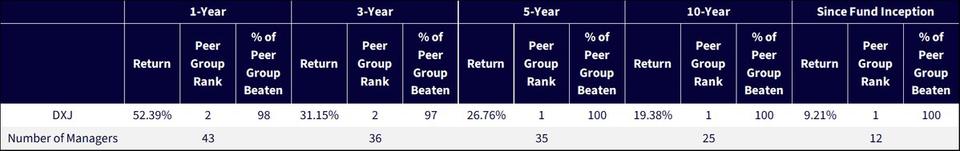
In Figure 1b, we see the numbers that DXJ has put up relative to the Morningstar Japan Stock Category:
- 1-Year: #2 out of 43
- 3-Year: #2 out of 36
- 5-Year: #1 out of 35
- 10-Year: #1 out of 25
- Since Fund Inception: #1 out of 12
Often, creating an investment strategy that achieves top-quartile, quintile or decile is viewed as strong. Here we are talking about literal number 1 and number 2 performance.
Figure 1a: Standardized Performance
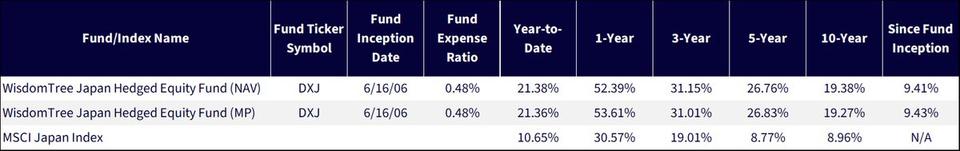
Figure 1b: DXJ’s Rankings in the Morningstar Japan Stock Category (6/30/2026)
Sources: For Figure 1a: Morningstar, FactSet and WisdomTree. Specifically, data is from the PATH Fund Comparison Tool, accessed as of July 15, 2026, but showing returns for the period ended June 30, 2026. NAV denotes total return performance at net asset value. MP denotes market price performance. Figure 1b: Morningstar Direct, with all results shown for the Morningstar Japan Stock category. Morningstar, Inc., 2019. All rights reserved. The information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. Past performance, rankings and ratings are no guarantee of future results. The % of Peer Group Beaten is the fund’s total-return percentile rank compared to all funds within the same Morningstar Category and is subject to change each month. Regarding ranking of funds, 1 = Best. Past performance is not indicative of future results. Investment return and principal value of an investment will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original cost. Current performance may be lower or higher than the performance data quoted. For the most recent month-end and standardized performance, click here.
How Did DXJ Do it?
DXJ is designed to track the total return performance of, before fees and expenses, the WisdomTree Japan Hedged Equity Index. For any index, it is important to consider two main elements:
- Stock Selection: The most selective criterion is a requirement that less than 80% of revenue comes from within Japan, the mechanism that tilts the portfolio toward exporters. A secondary screen requires dividend payment, though in practice this eliminates few major holdings, given how broadly Japanese companies tend to distribute dividends.
- Weighting: The index weights each constituent by the cash dividends it paid over the prior year, expressed as a share of total dividends paid across all constituents. The practical implication: a company with strong price performance but a flat dividend would likely see its weight reduced, while one with a growing dividend but flat equity performance would see its weight rise. Relative to float-adjusted market cap or price-weighted alternatives, this methodology can produce meaningful exposure differences, and carries the added benefit of potentially moderating valuation risk.
And Currency Exposure?
In 2026, currency exposure is increasingly a choice rather than a given for U.S. investors allocating interna-tionally. DXJ has been neutralizing yen/dollar exchange rate exposure since 2010. Notably, a depreciating yen tends to enhance the competitiveness and earnings of Japan's globally-oriented companies, making currency performance a substantive part of the investment thesis rather than simply a risk control.
A common misconception is worth addressing directly. Neutralizing currency exposure means exactly that, removing the exchange rate's effect on total return. The strategy neither benefits when the yen depreciates nor is hurt when it appreciates. The investor's return is driven primarily by the underlying equities. There is an additional dimension worth noting: because U.S. interest rates have generally run above Japanese rates, DXJ investors have historically been paid to hedge through the carry embedded in currency forward contracts.
Conclusion
Japan's equity story has rarely been this coherently constructed. What makes the current moment distinctive is not any single catalyst but the alignment of several reinforcing forces:
- Corporate Japan delivering record profitability across the board.2
- A government committed to transformational capital deployment in the industries defining the next decade.3
- A sovereign wealth fund being directed, publicly and deliberately, toward domestic markets of a scale that commands attention.4
The Bank of Japan's gradual normalization adds a layer of discipline rather than disruption. A central bank that moves carefully, tethering each step to wage and demand evidence, is signaling confidence in the underlying economy rather than urgency to restrain it. That is a constructive backdrop, not a headwind.
For investors, the opportunity is to access all of this at a valuation that still reflects skepticism the underlying fundamentals no longer warrant. Japanese equities continue to trade at a meaningful discount to the broader market, with a dividend yield that more than compensates for that gap. When earnings momentum, policy conviction, and institutional capital flows converge at a discount to fair value, the case for allocation tends to make itself.
Japan, for once, is not asking investors to be patient. The evidence is already arriving.
1 Source: Bloomberg News. (2024, February 22). Japan's Nikkei closes at all-time high, surging past 1989 record. Bloomberg.
2 Source: The Japan Times. (2026, May 24). Japanese listed firms log record net profits in 2025. The Japan Times.
3 Source: The Japan Times. (2026, June 24). Japan unveils $2.3 trillion investment plan for next 14 years. The Japan Times.
4 Source: Reuters. (2026, July 13). Japan has no plans to overhaul pension funds' asset allocation, sources say. Yahoo Finance.
See the WisdomTree Glossary for definitions of terms and indexes.
Important Risks Related to this Article
There are risks associated with investing, including possible loss of principal. Foreign investing involves special risks, such as risk of loss from currency fluctuation or political or economic uncertainty. The Fund focuses its investments in Japan, thereby increasing the impact of events and developments in Japan that can adversely affect performance. Derivative investments can be volatile and these investments may be less liquid than other securities, and more sensitive to the effect of varied economic conditions. As this Fund can have a high concentration in some issuers, the Fund can be adversely impacted by changes affecting those issuers. Due to the investment strategy of this Fund, it may make higher capital gain distributions than other ETFs. The Fund invests in the securities included in, or representative of, its Index regardless of their investment merit and the Fund does not attempt to outperform its Index. Please read the Fund’s prospectus for specific details regarding the Fund’s risk profile.
Past performance is not indicative of future results.
U.S. investors only: Click here to obtain a WisdomTree ETF prospectus which contains investment objectives, risks, charges, expenses, and other information; read and consider carefully before investing.
WisdomTree Funds are distributed by Foreside Fund Services, LLC, in the U.S.
This WisdomTree article is provided as part of a paid sponsorship.
